About
About
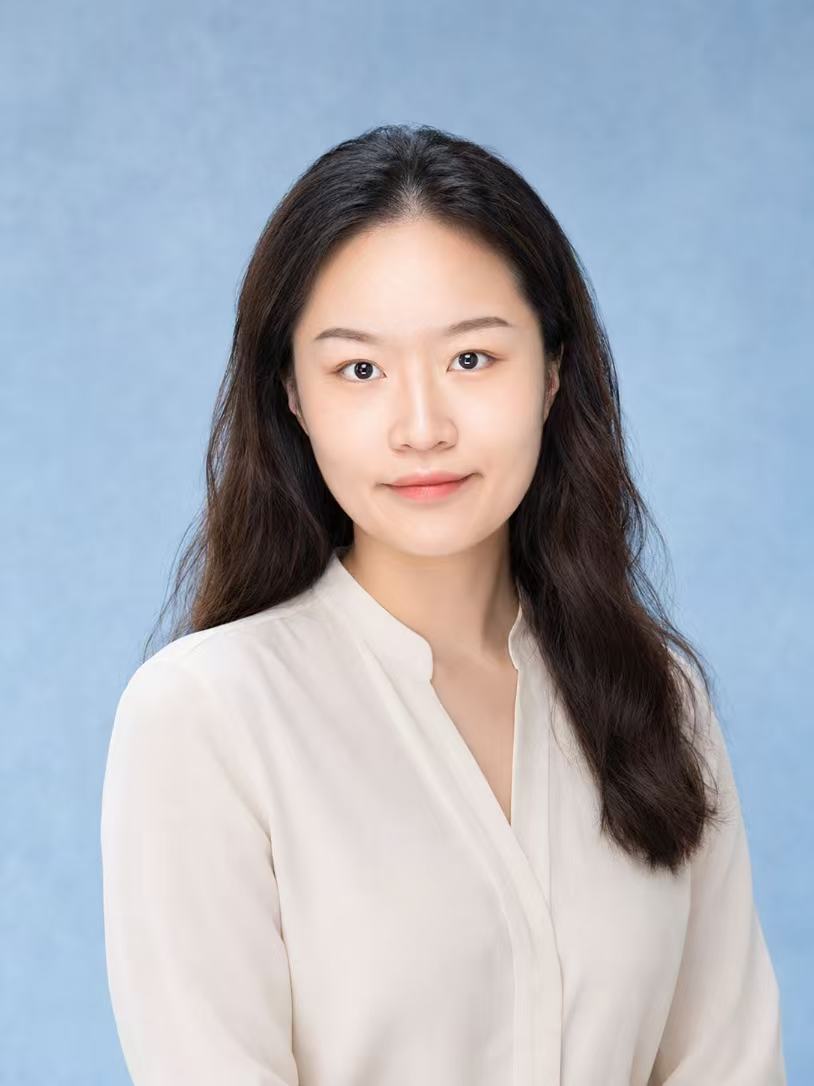
I am a PhD student in the Department of Econometrics and Business Statistics at Monash University. My research interests lie at the intersection of quantitative finance, portfolio choice, decision theory, and risk preferences.
My current research focuses on dynamic portfolio choice and preference modelling. In particular, I study how strength of preference can be distinguished from risk aversion in models of financial decision-making.
🎓 Education
Monash University
PhD in Econometrics and Business Statistics
Australia
Jul 2024 – Present
Research areas: quantitative finance, portfolio choice, decision theory, and risk preferences.
The University of Manchester
MSc in Mathematical Finance
United Kingdom
Sep 2022 – Nov 2023
Xi’an Jiaotong-Liverpool University
BSc in Financial Mathematics
China
Sep 2018 – Jul 2022
🧑🔬 Research Interests
- Quantitative finance
- Portfolio choice
- Decision theory
- Risk preferences
- Behavioural finance
- Risk analytics
💼 Experience
PhD Student / Researcher
Monash University
Jul 2024 – Present
Conducting research in quantitative finance, dynamic portfolio choice, recursive preferences, and decision theory. Current work focuses on distinguishing strength of preference from risk aversion in models of portfolio choice and narrow framing.
Teaching Associate / Tutor
Monash University
Jul 2025 – Present
Facilitated tutorials for quantitative finance, explaining mathematical models, portfolio choice concepts, and problem-solving techniques. Provided academic support during tutorials and consultation sessions.
📧 Contact Information
- Email: zixuan.fang@monash.edu
- LinkedIn: Zixuan Fang
- CV: Download CV